In 2025, Brown & Sterling was honored to be included on the Inc. 5000 list, ranking No. 3373 among the fastest-growing private companies in America. As a small firm, this recognition meant a lot to us. It reflected not only where we had been, but the growth, trust, and momentum we had built over the prior three years.
Brown & Sterling was selected based on 117% three-year growth, a milestone we are incredibly proud of and grateful for. That growth was made possible by our clients, our team, and the entrepreneurs and business owners who trusted us to help guide their tax strategy and long-term planning.
This recognition also marked an exciting step forward for our firm. As Brown & Sterling continues to grow, we remain focused on the same things that got us here: thoughtful guidance, strong client relationships, and high-level tax strategy designed to support business owners as they enter their next chapter.
A heartfelt thank you to our incredible team — you helped make Brown & Sterling one of Washington’s Best Workplaces once again!
We are honored to be recognized by Puget Sound Business Journal as one of the Best Workplaces 2025. This recognition is especially meaningful because it is based directly on employee feedback and workplace satisfaction surveys.
This year, Brown & Sterling was ranked #5 in the category for companies with 10–24 employees. Out of hundreds of organizations across Washington, being recognized among the state’s top workplaces is a reflection of the culture our team creates every day.
At Brown & Sterling, we believe a strong workplace is built on trust, service, collaboration, and caring for one another. We are proud of the environment our employees have helped shape — one where people are encouraged to grow professionally while doing meaningful work that serves our community and clients.
To every member of our team: thank you for your dedication, positivity, and commitment to excellence. This honor belongs to all of you, and we are grateful for the opportunity to work alongside such an outstanding group of people every day.
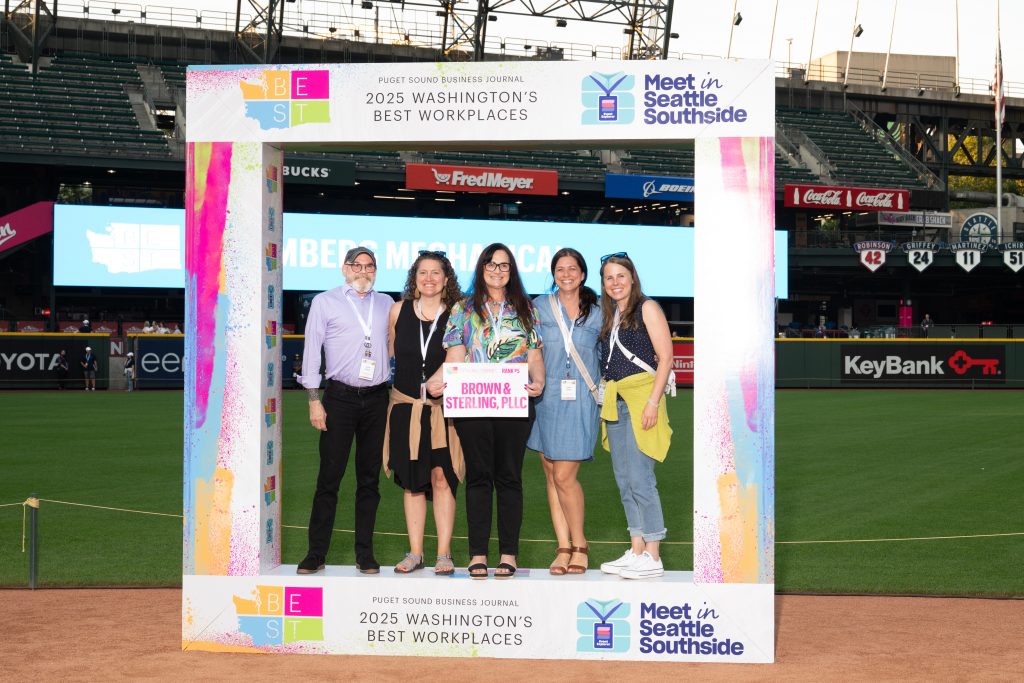
Several members of the Brown & Sterling team. From Left to Right:
Dave Lawson – Operations Manager; Crystal Quinn, Administrative Asst.; Jennifer Reardon, Managing Partner; Steffen Hefley, Senior CPA, and Jennifer Santiago, Tax Administrator.
A big thank you to all of our employees – you made us one of Washington’s Best Workplaces!
Brown & Sterling is honored to be named one of Puget Sound Business Journal’s Best Workplaces 2019!

Photo Carol Ladwig/SVR
Brown and Sterling is Number 4 for Small Business on Puget Sound Business Journal’s annual list of the 25 best places to work in Washington – this is a fantastic honor that comes directly from our people! Employee survey responses created the score that put us in the top spot, out of hundreds of applicants, as one of the region’s top employers.

Encompass Board of Trustees
We are pleased to announce that Lawrence Brown has been awarded the 2018 Outstanding Contribution in Human Services Award through The Alliance of Eastside Agencies for his contributions to North Bend based Encompass who provide vital services to areas families. Through Larry’s commitment to providing services and guidance, Brown & Sterling is proud to help promote the success of Encompass and the families they serve.
The following is from the AEA press release:
“AEA is pleased to honor members of the community who have played a significant role in supporting human services in East King County. This event highlights the work of those in the community who make the Eastside a better place for all of us to live and work.”
Read more at the Bellevue Reporter
A big thank you to all of our employees – you made us one of Washington’s Best Workplaces!
Brown & Sterling is honored to be named one of Puget Sound Business Journal’s Best Workplaces 2017!
Photo Carol Ladwig/SVR
Brown and Sterling is Number 17 for Small Business on Puget Sound Business Journal’s annual list of the 80 best places to work in Washington – this is a fantastic honor that comes directly from our people! Employee survey responses created the score that put us in the top spot, out of hundreds of applicants, as one of the region’s top employers.
Be sure to also check out the coverage of this award in the Snoqualmie Valley Record.
 You probably saw the Anheuser-Busch ad during the Super Bowl. You know the one, it went somewhat viral after the game because a lot of people saw it as some kind of comment on immigration.
Regardless of one’s political leanings, it was an effective ad – two immigrants meeting in St. Louis around the time of the Civil War and launching Budweiser. Coors, of course, has a parallel story, almost at exactly the same time Anheuser and Busch met, Adolph Coors was getting his brewery up and running just a little way to the west.
The rest, as they say, is history, by the 1980’s Anheuser-Busch and Coors were the first and fourth largest breweries in the United States. In third place was Stroh’s. Stroh’s . . . you can be forgiven for never having heard of them, never mind ever sipping one.
Yet, in the early 1980’s Stroh’s was a household – well, at least a beer-drinker-in-the-mid-west household – name. Even if you never had a Stroh’s you had heard of them. Like Coors and Budweiser, Stroh’s was founded by an immigrant in the mid-1850s. Like the Coors, Anheusers, and Buschs, Stroh’s started as a family business. Like the Coors, Anheusers, and Buschs, the Stroh’s passed the business down for four generations.
Unlike the Coors, Anheusers, and Buschs, the Stroh’s didn’t survive and thrive into the 1990s. Neither did the Stroh’s family fortune, at one time one of the largest family fortunes in the United States.
It’s not often that real life allows a direct comparison of companies over a century like a business school problem, but that’s the Coors, Anheuser-Busch, Stroh’s scenario. Family businesses that made it – while surviving Prohibition, no less – from the Civil War through to the Reagan years.
Then, in the space of ten years or so, there were two.
As you can probably guess, there is no one reason for Stroh’s demise, there are many. But they all revolve around one theme, bad planning.
Not bad decisions, bad decisions can be rectified, overcome within a good plan. It seems that Stroh’s never really had a plan for the future until the future was on top of them. Which, of course, is too late.
Stroh’s made beer in Detroit. They marketed mostly to the Mid-West. They, obviously, had a great, loyal  following. They had decided generations earlier that only the men of the family would run it, no women, no outsiders. They had decided generations earlier that every family member would get dividends for life … regardless. An easy thing to support through a generation or so, but by 1980 Stroh’s dividends were paying for the lavish lifestyles of some twenty-seven family members, only a few of whom were working in the business.
It’s easy to imagine the business being run like a large, benevolent fiefdom. Stroh’s had an entrenched market, but made the mistake of becoming entrenched as a company. After one hundred and twenty years of success doing it the ‘family way’ no one running the company apparently saw change coming, certainly never thought to plan ahead.
So, when change did come, it – as change has a way of doing – came fast and Stroh’s wasn’t ready. What happened to start it off is what happens to all successful companies across the spectrum of industries, a competitor began to push. In Stroh’s case it was their fellow-immigrant founded in the mid-1800’s company, Coors.
Coors was spreading eastward. By the late ’80s their sales were poised to surpass Stroh’s. Stroh’s management wasn’t ready. They seem to have panicked. In a short period of time they tried a series of increasingly ill-advised, knee-jerk-like reactions. None worked, just piled debt into the equation. By the time Stroh’s had to fire-sale their assets, including the Stroh’s brand, they had even tried to diversify into bio-tech.
It all gets us thinking – the only companies that need planning more than start-ups are established, successful ones.
We posted a quick piece about the World Chess Championship now being played in New York City. The website FiveThiryEight has a running commentary on the matches, we shared one of them with a note about chess and planning … you know the deal, it’s a metaphor made fairly often.
But, upon some deeper reflection, it’s not really a perfect metaphor. It’s easy one to use (too easy?) – you know, ‘business planning is like chess, every time you move the board changes and you have to re-plan and re-think, move again and then go through it all over again until at last …. That part, ‘at last’ is the problem, I think. Because, no matter how you look at it, people play chess to win.
This simple yet vitally important fact is too often overlooked.
 Chess is a great intellectual exercise but the minute two people are sitting across from one another make no mistake, it’s about winning. The two men playing by the South Street Seaport in Manhattan, Magnus Carlsen of Norway, the defending world champion and Sergey Karjakin of Russia, currently the seventh ranked player in the world, are certainly only thinking of winning.
Any thoughts you might have that chess isn’t every bit as competitive as football or hockey or … anything, will be instantly dispelled watching last year’s Pawn Sacrifice, the story of the Bobby Fisher – Boris Spassky chess championship in the early ’70s. Toby McGuire did an amazing job portraying Fisher and his mental deterioration. The movie takes the position, clearly, that the stresses of high-level chess played a big part in that deterioration. Winning is everything.
I’m struck by this – it’s from the film but it’s also directly from Fisher’s life: In an interview with a magazine, Fischer’s coach explains to an uninitiated reporter, “after the first four moves of any chess game there are 300 billion possible move combinations.”
Sure, that’s a staggering amount of combinations and, on a lesser scale, it does conjure images of working through a a business plan. Or sale. Or purchase. It’s Fischer’s response to his coach’s assertion that blows the metaphor apart: “People think there are all these options, but there is only one right move.”
“Only one right move.” It’s true for chess. A million, million possible combinations after every move, but only one right one if you want to win. Need to win.
That’s not remotely true with business planning – in any of it’s variations. There are many right moves, it’s just that the order of them can sometimes be vital. It’s never about winning – even business sales and purchases- it’s about doing it right and continuing to be successful. Chess players have to win to be successful, business owners just have to plan, be smart, and think ahead – like a great chess player.
Ever seen that 2004 movie Raising Helen? The one in which Kate Hudson played a free-spirited and self-obsessed modeling agency assistant who suddenly finds herself raising her sister’s three orphaned kids? We all shook our heads as she tried to fit a trio of energetic youngsters into her glamorous lifestyle and failed miserably- or so we thought. Then, in true Hollywood style, Helen grew up overnight and became the perfect mother: something her deceased sister had counted on her doing. (Hopefully the producers didn’t count on the movie being a box office hit, because it really wasn’t.)
Let’s rewind for a moment. When parents (like Helen’s sister) have a new baby, if they’re not changing diapers, feeding, playing or sharing pictures and stories on Facebook, they become preoccupied with planning for the baby’s future. They budget for college and make other decisions that set up the child for success. For many, the birth of a child will be the catalyst for their first estate planning documents, where they will name a legal guardian in case they aren’t around for that Ivy League graduation ceremony.
When you own a business, you’ve got to be like a parent and dedicate every waking hour to making your creation a success. Most of us have got that part down. But when it comes to the long term, we tend to be short sighted. Exit planning just isn’t part of the equation. But someday, all business owners have to leave their businesses. Ideally, that departure will be planned, so they can leave when they want and on the terms they want.
Perhaps the idea of turning over the company to someone else after you retire is something you don’t want to think about. So you avoid the subject and wait until the eleventh hour, never thinking that the outcome might not be what you hope for. Sometimes it isn’t even enough to retire on.
If you want your business to fund your retirement goals, you need to do more than assume, “Someone will want to buy it.” Sure, someone will, but without a carefully thought-out strategy, the payout might not be what you hoped for. It might result in a bigger financial disaster than Raising Helen.
The person or entity that buys your company will essentially be its legal guardian once you’re out of the picture. Just as a parent would not trust their child’s future to anyone they hadn’t thoroughly vetted beforehand, you want to make sure that potential buyers are qualified. Do they have the business acumen and management experience and ability to keep growing the company? And, for the sake of your own future, do they have the financial ability to pay the amount you’re asking?
It’s not just your company’s future at stake when you prepare to hand over the reins. It’s yours too. Start planning now. When the changing of the guard finally takes place, you -and your corporate offspring- will be set up for the best possible outcome. Maybe they’ll even make a movie about it.
Every so often you’ll see a story on the news about someone who made a fortune off of some toy collection from their childhood or by selling a random antique they found at a yard sale. We even have numerous TV shows dedicated to the discovery and sale of tangible assets, especially items that seemed like nothing more than junk to the owner.
Shows like Pawn Stars and Antiques Roadshow keep the dream alive of becoming immensely wealthy by collecting and preserving everyday items that may someday drastically increase in value and provide an outrageously high ROI. They have fed into an already massive “Cult of Collection” whose ranks are filled out by garage sale hoppers, flea market bargain hunters, and abandoned storage unit scourers who are hoping to strike it rich.
Unfortunately, shows like these have likely inspired many more hoarders than they have millionaires. Nonetheless, many of you reading this at some point probably started a collection of mint condition comic books or baseball cards or Beanie Babies or Star Wars figurines in hopes that someday they would appreciate in value. Maybe you even hermetically sealed them and stashed them away in a dark closet or storage unit to ensure they were properly preserved. And if you have the time and patience and discipline to be a true collector, perhaps that investment will pay off…someday.
But the truth is, you have very little to no control over whether or not these assets will ever appreciate in value, and it’s a lot more fun to take them out of the box and play with them.
One asset that does afford you immense control over its value? Your business.
Unlike comic books or baseball cards, there are many steps you can take to increase the potential sale value of your business, and you won’t even have to hide it in a closet.
Start by working to transform your business from a work-in-progress to a turnkey enterprise. Most potential buyers will not want to have to put a lot of time or effort into building and growing your business once they take over. They will want to be able to step in and do as little as possible to profit from the purchase. To achieve turnkey status, you will want to focus on systematizing and simplifying your company’s processes while ensuring you have employees in place who can help ensure any transition to a new owner will be as seamless as possible.
And it should go without saying that working to increase your company’s profitability will also help to improve its value. And remember, a recurring form of revenue is generally going to be much more valuable from a business valuation standpoint than that of a one-time sale.
If you’re the type who is hoping to make a fortune off of his or her comic book collection, we wish you the very best of luck. But if you’re the type who wants to take control of your future by learning more about business exit planning and discovering strategies to help you boost the potential sale value of your company, please call the attorneys at Brown & Sterling today.
Ever heard of the Ford Flivver? It’s not a model you would have seen around town while driving to the grocery store. In fact, the only place you can still find one is in the Henry Ford Museum. The Ford Flivver—dubbed the “Model T of the sky”—was Henry Ford’s failed attempt to bring planes to the masses, and it is one of the earliest signs we can point to of the start of man’s expectations of flying cars.
For decades, portrayals of “The Future” in popular culture have included flying cars as symbols of technological advancement. From The Jetsons to Star Wars, man has viewed the flying car as the pinnacle of what we can achieve, with plenty of confidence that flying vehicles will be just around the corner. Ford himself said in 1940, “Mark my words: a combination airplane and motorcar is coming. You may smile, but it will come.”
Now, 76 years later, where are all the flying cars we’ve all been waiting on? We’ve sent men to the moon and back, airplanes routinely fly around the world with hundreds of passengers, but no flying cars.
Perhaps it is time to reset our expectations about the “car of the future.” Instead of flying cars, it is becoming clear that automated cars will be the next big futuristic advancement in travel. In fact, Google already has numerous prototype self-driving cars out being tested on public streets, and thirty or more other companies are all investing in developing their own versions of self-driven cars, including Uber, Apple, Microsoft, Tesla, and most traditional car manufacturers. Ford may not be trying to put cars in the sky anymore—at least for now—but they too are trying to get in on the self-driven car boom.
So what is the appeal of the self-driving car? Like many things in our lives, we seek to make them more efficient by making them more autonomous. The goal of such autonomy through the use of any technology is to help minimize both human effort and error. In the case of our cars, it is meant to make our lives as easy as possible as we transition from one place to another.
Know what else benefits from being autonomous? Your business. Ask yourself, could your company continue to run unhindered without your involvement? Have you actually crafted a “self-driving company?” or would things fall apart as soon as you left?
These are incredibly important questions for every business owner to ask themselves, especially as they begin to consider their exit strategy. Having an autonomous business means you’ve developed a structure of people and assets which operate smoothly and efficiently without you personally having to do anything. It means efficiency, profitability, and perhaps most important, a smooth transition from one owner to the next when the time comes to sell your business.
If you want to get an optimal cash offer when the time comes to sell your business, it is absolutely essential that your company be just like Google’s self-driving cars of the future: able to keep operating like normal no matter who is in the front seat.
For legal guidance regarding how to structure your company so as to make it as autonomous as possible, as well as in-depth business exit strategy planning, please contact the law office of Brown & Sterling today!